

Trulioo: Broker Onboarding, UBO Discovery and Business Risk
Trulioo provides identity verification, business verification, ownership research and screening tools that can be combined within customer onboarding workflows. For forex brokers, the proposition covers both retail applicants and corporate accounts: checking a person’s identity, establishing that a business exists, identifying the people behind it and reviewing relevant financial-crime signals. Its expanding business-risk products add another layer, turning company information and research findings into evidence that a risk team can use in its own decisions.
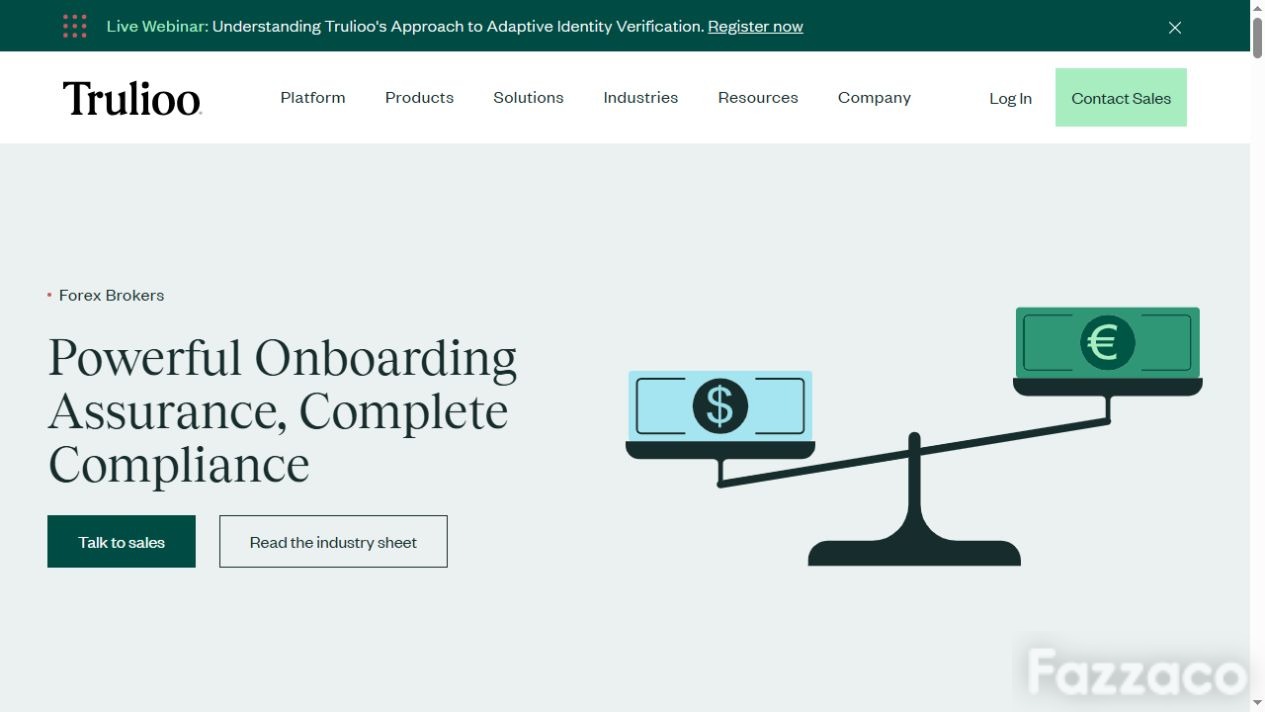
Trulioo’s forex broker onboarding page. Image: Trulioo.
A platform connecting personal and business identity
Trulioo’s forex offering brings data checks, document and biometric verification, business verification and AML screening into configurable workflows. The company describes a drag-and-drop Workflow Studio for adjusting the sequence of checks. This is useful where different applicants need different evidence: a retail trader may follow an individual verification path, while a corporate account needs company information, ownership details and checks on associated people.
The platform’s role is to supply verification results and risk information to the firm operating that workflow. It does not replace the broker’s customer policy or the account-opening decision. Combining several checks in one interface can reduce integration fragmentation, but a broker must still define what constitutes sufficient evidence, when a case needs review and which internal system records the outcome.
This distinction is particularly important for firms serving multiple markets. A consistent interface does not mean identical underlying data is available everywhere. Trulioo itself notes that available checks depend on the product, market and configuration. Rollout planning therefore needs to start with the broker’s actual customer mix, rather than treating a global product description as a guarantee for every application.
Retail onboarding through a blend of verification methods
Trulioo’s person-verification offering combines identity data, document verification, biometrics and supported digital identities. These methods address related but different questions. Data matching compares submitted information with available records. Document checks examine the evidence a person presents. Biometric checks help connect the applicant to that evidence. The appropriate combination depends on the information already available and the uncertainty that remains.
A broker can use that range to design a journey with proportionate escalation. An application that cannot be resolved using one method may need additional evidence rather than a repeated request for the same information. The operational benefit comes from making the next step clear to the applicant and the reviewer. An unexplained failure message can create customer-service work even when the underlying verification technology has correctly identified a missing or inconsistent field.
Testing should include ordinary variations in names, addresses, documents and device quality, not only a demonstration account that passes on the first attempt. Teams need to understand which results are definitive, which are incomplete and which require human judgment. Verification completion and account acceptance should remain distinguishable in the CRM so that a successful identity check is not mistaken for completion of every onboarding requirement.
Corporate accounts require a connected ownership picture
For corporate onboarding, Trulioo’s business-verification capabilities check company information and support investigation of ownership and associated individuals. The forex page specifically describes verifying institutional investors and ultimate beneficial owners through an onboarding workflow. This is a different task from checking the identity of a single representative: a valid personal identity alone does not explain the company’s ownership structure or the representative’s authority.
Company names and registration details provide the starting point. The more difficult work often begins when ownership passes through several entities or jurisdictions. A business may have a clear registry entry while the route to the people ultimately behind it remains incomplete. The quality of the resulting customer file depends on preserving the relationships between those entities, the supporting records and any unresolved questions.
For a broker, this suggests keeping company verification, ownership findings and personal checks as connected evidence rather than independent pass-or-fail boxes. A change in a director, owner or authorised representative may affect a different part of that record. The implementation should make those distinctions visible to the team responsible for reviewing the corporate relationship.
UBO Discovery adds research beyond registry retrieval
Trulioo presents UBO Discovery as a workflow with three layers: authoritative data, the Trulioo Business Graph and an AI agent for ownership research. Government registries, partners and hosted databases form the foundation. The graph supports relationship mapping across businesses and borders. The research layer examines sources such as filings, disclosures, legal records, public information and verified databases when the initial records are insufficient.
The important product distinction is between retrieving a company record and reconstructing an ownership chain. Trulioo says its discovery process categorises and reconciles sources according to reliability, recency and relevance, cites findings and reports gaps when it cannot resolve a relationship. Those features give analysts material to inspect instead of requiring them to accept an unexplained conclusion.
That does not make an inferred relationship equivalent to a fully evidenced ownership finding. In a procurement exercise, a broker should ask to see the underlying documents, the dates attached to them and how conflicting information is presented. A deliberately difficult sample, such as a multilayered company with sparse public records, is more informative than a simple company whose owners appear clearly in a single register.
Trulioo describes UBO Discovery as operating within a KYB workflow through a single API call. The integration benefit is that discovery can remain connected to the company case. The review requirement remains: the broker needs a process for resolving gaps, collecting additional evidence and documenting why the available information is adequate for its intended relationship.
Business Risk Horizon separates verification from risk assessment
Business Risk Horizon extends Trulioo’s business data with research and explainable risk signals. The product describes an overall score from zero to 100 alongside five domain scores: Business Model, Financial Health, Fraud and Financial Crimes, Governance and Compliance, and Third-Party and Market risk. Findings include supporting evidence and a plain-language rationale, while the customer applies its own policies and thresholds.
A verified registration and a risk assessment are distinct outputs. Registration information can establish which company is being considered without resolving whether its activities, relationships or inconsistencies warrant closer scrutiny. Horizon’s examples include address mismatches, virtual offices, layered ownership and connections to restricted jurisdictions. Each is a signal to interpret in context, rather than an automatic conclusion about the business.
The product is marketed for uses including merchant and seller onboarding, enhanced due diligence and assessment before granting businesses access to AI models. A brokerage considering it for corporate-account review should validate that specific use with the provider and test the findings against its own case requirements. The published examples do not establish a ready-made brokerage credit model, trading limit or counterparty-risk decision.
Data sufficiency also matters. A low-information case should not silently become equivalent to a low-risk case. During evaluation, analysts should examine how the product indicates missing evidence, explains the direction of a signal and allows the firm to use individual findings alongside its existing controls. The score is most useful when it helps organise scrutiny without hiding the uncertainty behind it.
Screening and fraud signals around the customer relationship
Trulioo offers sanctions, politically exposed person and adverse-media screening for people and businesses, including ongoing screening. For corporate accounts, that means the relevant subject can be the company or an associated individual. An apparent match still needs enough context for a reviewer to determine whether it concerns the actual customer and what action follows.
The platform also lists fraud capabilities using email, phone, IP, device and behavioural signals. These can add context to an application that otherwise appears consistent on paper. Their value depends on how they affect the workflow: whether they trigger additional verification, create a review task or contribute information to an existing case. A risk signal should remain explainable to the staff who must act on it.
Continuing screening adds a further operational requirement. The firm needs to decide how a changed result reaches the responsible team and how the review outcome is reflected in customer records. Ongoing screening should not be assumed to include every form of transaction monitoring or trading surveillance. The selected products and their actual event coverage need to be specified separately.
Integration and control over the decision
Trulioo provides APIs and developer documentation for bringing verification results and risk signals into existing applications. Its current platform also offers MCP integration for supported business-verification tools, allowing AI agents to access those capabilities. That integration is separate from Know Your Agent, which links an AI agent to a verified organisation using a signed credential and an authorised scope.
For most brokerage onboarding projects, the immediate priority is simpler: make sure the customer identifier, company case and verification result stay aligned across systems. Engineers should test incomplete responses, retries, duplicate submissions and cases awaiting manual review. Operations teams should be able to tell whether a customer is waiting for instructions, whether a service is still processing the request or whether a decision is ready.
Access, evidence retention and change control also need clear ownership. A compliance reviewer may require source documents and the reasoning behind an assessment, while a customer-service agent may need only the next action. Before launch, the firm should establish which records it receives, how they are retrieved and how workflow changes are approved. A configurable platform is easier to govern when changes to its rules are treated as business decisions with accountable owners.
Where Trulioo fits in a broker’s procurement shortlist
Trulioo is relevant to brokers looking to connect retail identity verification with more involved corporate onboarding and ownership research. Its business products provide a way to investigate relationships and organise risk evidence, while its person-verification and screening capabilities support the wider customer journey. The implementation scope will differ substantially between a firm seeking a limited identity check and one assembling an integrated corporate due-diligence process.
A useful pilot should include representative retail applications, a straightforward company, a layered ownership structure, an unresolved ownership case and a potential screening match. Compare the evidence delivered, the work left for analysts and the time customers spend completing additional steps. Those observations establish whether the configured service improves the broker’s actual operating process, rather than relying on broad coverage or automation claims.
 Subscribe Now