


Legal Cases and Beyond: Disputes Between IS Prime, Think Markets, and ISFE 21 (PART II)
IS Prime filed two lawsuits against ThinkMarkets. Now it's time for ThinkMarkets to fight back. In a counterclaim, Think accused IS Prime of breaching contract and causing huge losses to Think.
Third Summary Judgment
The third summary judgment published in early May showed that Think sought counterclaim against IS Prime, and ISFE 21 Ltd (ISFE 21), an affiliated company, was also joined as a Part 20 Defendant.
Think's main focus was IS Prime' obligation under the Liquidity Addendum to provide prices in Available Products which exactly matched the prices which IS Prime obtained from its own liquidity providers. Think alleged that IS Prime was not entitled to apply its own margin to those prices but was instead to replicate the same prices in its dealings with Think.
Nevertheless, in this case, IS Prime did not itself deal directly with the Tier 1 providers. Instead, its own trades were intermediated via back to back transactions with ISFE 21. This latter company did apply its own margins to the Tier 1 prices obtained from liquidity providers, with the result that it was those prices, rather than the "raw" Tier 1 prices, which were offered by IS Prime to Think and which were then used by Think (together with whatever further margin Think added) in their dealings with their own customers.
Think adopted a hybrid model when dealing with customers. In other words, Think combined A Book and B Book. Nauman Anees, CEO of Think, admitted that Think "executed A-book trades and B-book trades on a 30% - 70% split, respectively. Further, approximately 60-65% of revenue derived from profits on the B-book. Commission revenue represented less than 10% and mark-ups on pricing (applicable to both A-book and B-book trades) made up the remaining 25-30%."
In terms of A Book, Think's transactions with their customers, whether for purchase or sale, would be hedged with IS Prime, and IS Prime's transactions would be hedged with ISFE 21. Think contended and assumed that ISFE 21 rebated to IS Prime some or all of the "profit" it earned (whether by matching its transactions with the liquidity providers or by internalising the transactions onto its own book) and retained the rest.
B-book trades were not hedged with IS Prime, as the risk was internalised by Think. However, the prices made available by IS Prime were in fact used and such prices were, so it is alleged, "uncompetitive", and their use caused Think loss.
Think alleged that
-The Liquidity Addendum, alternatively each trade executed under the Liquidity Addendum, is liable to be rescinded and declared void or voidable for deceit and misrepresentation, and Think are entitled to "restitution and damages."
-IS Prime and ISFE 21 obtained "secret profits", with the result that Think are entitled to rescind the trades with IS Prime and to the "recovery of money held on trust, restitution, damages and/or an account of profits". The premise of this allegation is the further contention that IS Prime owed and breached fiduciary duties to Think when executing trades under the Liquidity Addendum.
-IS Prime and ISFE 21 Ltd are liable in damages for unlawful means conspiracy, alternatively lawful means conspiracy.
-IS Prime committed "repudiatory" breaches of contract, sounding in damages.
The counterclaim was amended after IS Prime and ISFE 21 applied to strike out some paragraphs. Finally, the judge ruled that "Paragraphs 66 to 70 of the Re-Amended Defence and Counterclaim are struck out. Paragraph 71 is not struck out and nor is summary judgment given on IS Prime's pleaded response to that paragraph."
However, the judge also stated that "paragraph 71 currently suffers from a lack of detail, obscurity and potential inconsistency, and there are also broader concerns about how the methodology of calculation fits with the breaches of duty and other causes of action alleged. The sums claimed in the paragraph are large and it is in the parties' interests to have clarity about this claim, not least for the purposes of disclosure and expert evidence."
In Paragraph 71, Think claimed that their "best estimate of this loss figure is between $17,094,496 and $20,329,798.”
Covert ISFE 21
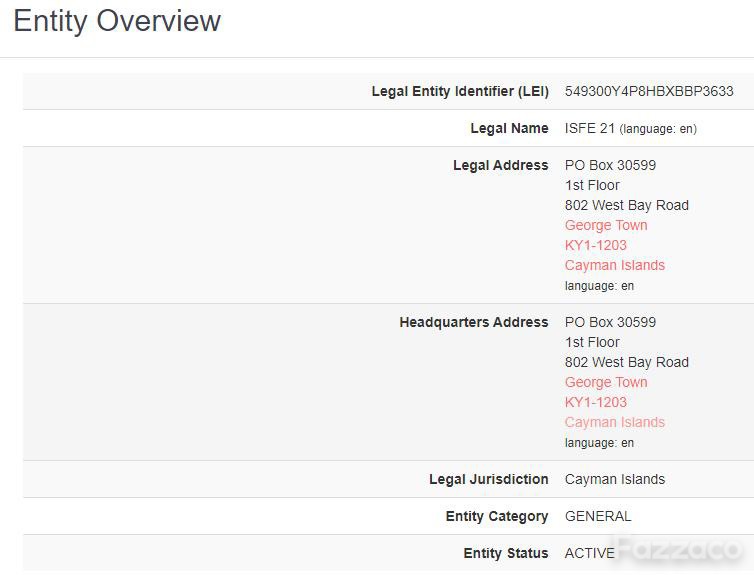
The third summary judgment also involved ISFE 21, an affiliated company. Its basic info was listed below.
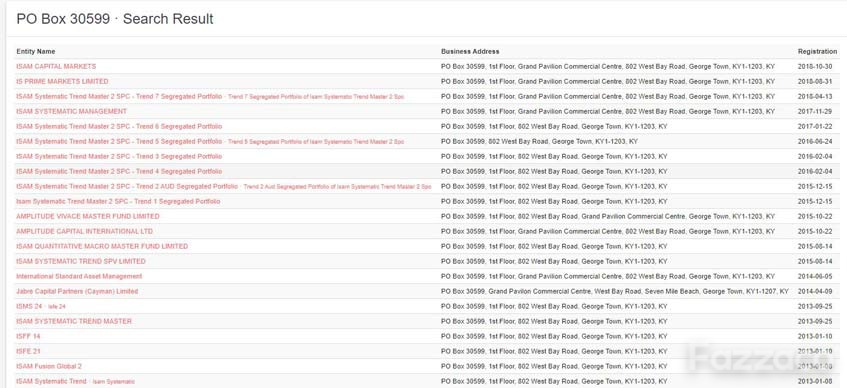
 Fazzaco's investigation found that many other companies share the same location.
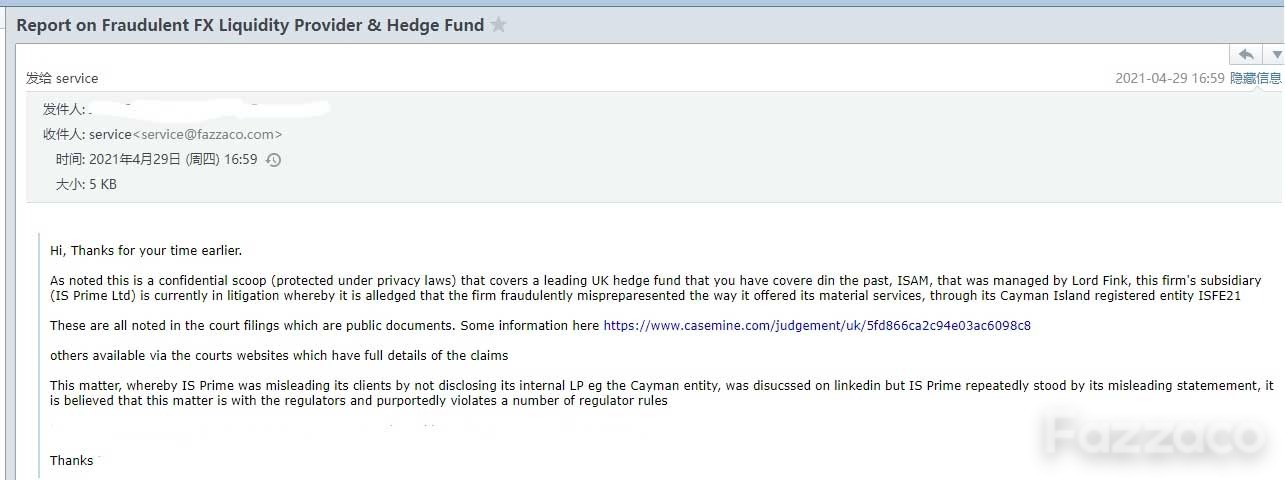
 In fact, Fazzaco received a report from our user, stating that IS Prime fraudulently misrepresented the way it offered its material services through ISFE 21 in April, 2021.
 It is understandable that companies in the forex industry incorporate in Cayman Islands. But in this case, Think's main concern is ISFE 21's role as an intermediary company that added spreads before sending the price back to IS Prime and then to Think.
What other facts can be found about IS Prime? Did others doubt IS Prime's liquidity? The story continues.
 Subscribe Now

